Spain’s minimum wage: €1,221 now, €1,286 proposed for 2027. What it means for autónomos
Spain’s minimum wage (SMI) in 2026 is €1,221 a month, paid 14 times a year. On 4 November the Ministry of Labour proposed raising it to €1,286 from 2027, but the decree has not been approved yet. Working from the BOE, Spain’s official gazette, we calculated what a minimum-wage employee takes home, what they cost an autónomo and how the minimum wage ties in with residence permits.

Spain’s minimum wage is rising faster than other pay, ABC reported on 14 November. The trigger was the draft decree setting the minimum wage for 2027. We went through the BOE and ministry documents to separate what is already law from what is still a plan. Then we did the sums for anyone with staff: how much a minimum-wage employee takes home and how much they cost an autónomo (a self-employed person).
In this article
What is the minimum wage in Spain now?
In Spanish the minimum wage is the salario mínimo interprofesional, or SMI for short. The 2026 rate was set by Royal Decree 126/2026 of 18 February. It was published in the BOE on 19 February and applies retroactively from 1 January to 31 December 2026. Compared with 2025, the minimum went up by 3.1%, from €1,184 to €1,221 a month.
Spanish salaries are usually paid 14 times a year: 12 monthly payments plus two extra ones, the pagas extra. By law one of them falls at Christmas, and the month of the other is set by the sector’s collective agreement (convenio colectivo). If a contract spreads the extras across the year, the minimum works out at €17,094 / 12 = €1,424.50 a month.
| 2026, in force | 2027, proposed | |
|---|---|---|
| Per month, 14 payments a year | €1,221 | €1,286 |
| Per month, extras spread over 12 | €1,424.50 | €1,500.33 |
| Per day | €40.70 | €42.87 |
| Per year | €17,094 | €18,004 |
| Temporary contract of up to 120 days, per working day | €57.82 | €60.88 |
| Domestic staff paid by the hour | €9.55 an hour | €10.06 an hour |
The amounts in the decree are for a full legal working week. Part-timers are paid the minimum pro rata to their hours. Housing, meals and other payment in kind do not reduce the cash part: the employee must receive €1,221 in cash.
What has been proposed for 2027?
On the evening of 4 November the Ministry of Labour opened public consultation on the draft SMI decree for 2027. Comments are accepted until 16 November. The draft proposes a 5.3% rise: €1,286 a month, €42.87 a day, €18,004 a year. The new amounts would apply from 1 January 2027.
The explanatory report attached to the draft says where the 5.3% comes from. On 3 November the ministry’s expert committee recommended raising the minimum by 4.9%, in line with the provisional inflation figure for October, which would mean €1,281. The ministry added another 0.4 percentage points. Between January and October 2026 prices rose by an average of 3.5%, while this year’s SMI went up by only 3.1%, so the government decided to make up the difference.
For now it is only a draft. It becomes law once the Council of Ministers approves it and it is published in the BOE. The government wants this done before the general election on 29 November. The employers’ organisations CEOE and Cepyme object to the decree being passed in the run-up to the vote, the EFE news agency reports. As of 15 November 2026, the rate in force is €1,221.
Who the SMI applies to
The minimum is compulsory for everyone working in Spain on an employment contract, in any sector, regardless of sex or age. It is a floor. If the collective agreement for your sector in your province (convenio colectivo) sets higher pay, you pay that instead.
The comparison is made on annual pay. If an employee already earns more than the minimum once all bonuses and supplements are counted, the decree does not oblige you to give them a rise (article 3 of the decree). If they earn less, their pay has to be brought up to €17,094 a year for full-time work.
The SMI does not apply directly to autónomos themselves, because they do not pay themselves a salary. It does touch them in a few places, though, and we cover those below.
How much does a minimum-wage employee take home?
Employees pay their own share of Social Security (Seguridad Social) contributions out of their salary. In 2026 it is 6.50% of the contribution base (contributions order Orden PJC/297/2026): 4.70% for common contingencies (risks not connected with work), 1.55% for unemployment on a permanent contract, 0.10% for training and 0.15% to the MEI, the pensions reserve mechanism.
The contribution base includes a share of the two extra payments: 1,221 × 14 / 12 = €1,424.50. For most manual and support roles (contribution groups 4 to 11), the minimum base in 2026 is €1,424.40, so the figure from the salary is used.
- Employee contribution: 1,424.50 × 6.50% = €92.59 a month.
- Take-home pay in a normal month: 1,221 − 92.59 = €1,128.41.
- Take-home pay in a month with an extra payment: 2,442 − 92.59 = €2,349.41.
- For the year: 17,094 − 12 × 92.59 = €15,982.92.
If the extras are spread across the year, take-home pay is 1,424.50 − 92.59 = €1,331.91 every month. These figures are before IRPF income tax. Over the year, a minimum-wage employee ends up paying none, as explained below. Here and throughout, amounts are rounded to the cent and each contribution is worked out on the monthly base.
How much does a minimum-wage employee cost the employer?
On top of the salary, the employer pays its own share of contributions. The 2026 rates under the same order are 23.60% for common contingencies, 5.50% for unemployment (6.70% on a temporary contract), 0.20% to FOGASA, the wage guarantee fund, 0.60% for training and 0.75% to the MEI. There is also a contribution for workplace accidents and occupational illness (AT/EP), whose rate depends on the type of business. For restaurants and bars, hairdressers, beauty salons and office work it is 1.50%, for retail 1.65% and for building cleaning 3.60% (the scale in the 61st additional provision of the Social Security Act).

Full-time, permanent contract
Take a café or beauty salon on the 1.50% rate, where the employer’s total rate comes to 32.15%.
- Employer contributions per month: 1,424.50 × 32.15% = €457.98.
- Employer contributions per year: 12 × 457.98 = €5,495.76.
- Total for the year including salary: 17,094 + 5,495.76 = €22,589.76, an average of €1,882.48 a month.
In cleaning, where the rate is 3.60%, contributions come to €487.89 a month and the year costs €22,948.68. A temporary contract adds another 1.20 points for unemployment: at the 1.50% rate that makes €475.07 a month. These figures do not include fees for your gestor, the accountant or adviser who handles your payroll and paperwork.
Part-time, 20 hours a week
Half a full week is paid at half the minimum: €610.50 a month, €8,547 a year. Part-time work has its own floor for the contribution base: €8.58 for every hour worked (article 39 of the contributions order). In a month when the employee works all their contracted hours, that averages 86.67 hours and a base of €743.63. This is higher than the salary including the share of extras (€712.25), so contributions are calculated on it.
- Employer contributions: 743.63 × 32.15% = €239.08 a month.
- Employee contribution: 743.63 × 6.50% = €48.34, leaving €562.16 take-home in a normal month and €1,172.66 in a month with an extra payment.
- Annual cost to the employer: 8,547 + 12 × 239.08 = €11,415.96.
In months with annual leave or public holidays fewer hours are worked and the base is lower. Your gestor’s payroll software works out the exact figure for each month.
Domestic staff
Cleaners, nannies and carers hired by a household fall under a special contributions scheme, the Sistema Especial para Empleados de Hogar. The minimum for those paid by the hour who do not live in is €9.55 an hour. That already includes the extra payments and holiday pay (article 4 of the decree).
Contributions follow a table: monthly pay falls into one of eight bands, each with its own base. Households get reductions of 20% on the employer’s common contingencies contribution and 80% on unemployment and FOGASA contributions (first additional provision of RDL 16/2022). With these, the employer’s rate comes to 22.27% of the base: 18.88% for common contingencies, 1.50% for workplace accidents, 1.10% for unemployment, 0.04% to FOGASA and 0.75% to the MEI.
- A cleaner working 10 hours a week: an average of 43.33 hours a month × €9.55 = €413.83. That falls in the second band of the table (pay from €329.01 to €510), with a base of €436. The household pays €97.10 a month in contributions and the worker €27.90 (6.40% of the base, as domestic staff pay no vocational training contribution). In total the household spends about €510.93 a month.
- A full-time home help on the minimum wage: a base of €1,424.50 and a household contribution of €317.24 a month. The worker pays €91.17 and takes home €1,129.83 in a normal month.
Do minimum-wage employees pay IRPF income tax?
Not by the end of the year. Since 2026, anyone with employment income of up to €17,094 a year is entitled to a €590.89 reduction in the tax due. It was introduced by Royal Decree-Law RDL 5/2026 (article 28, 61st additional provision of the IRPF Act), and Congress approved it on 18 March 2026. The reduction cancels out the tax on the minimum wage. Between €17,094 and €20,048.45 it tapers off, and above that it disappears. There is one condition: income other than salary must not exceed €6,500 a year.
The reduction is applied in the annual tax return, the renta. The thresholds below which the employer withholds no tax at all from the salary have not changed since 2024 (article 81 of the IRPF Regulations). For a single person without children the threshold is €15,876 a year, less than the current SMI. So the payslip (nómina) of a minimum-wage employee may show a small withholding. It can be reclaimed through the tax return. Filing is compulsory with income above €22,000 from a single employer, but anyone can file voluntarily.
For 2027, the expert committee worked out the SMI on the basis that it should not be subject to IRPF. There is no tax rule for 2027 yet.
What the SMI changes for autónomos themselves
An autónomo’s monthly contribution does not depend on the minimum wage. Since 2023 it has been based on bands of net income, and the 2026 band amounts are set out in euros in the same contributions order. We explain how contributions and taxes work in “How to become autónomo in Spain in 2026”.
There are three cases, though, where the SMI does affect you.
The reduced flat rate in year two
For the first 12 months a new autónomo pays a reduced contribution, the tarifa plana. It can be extended for another 12 months if net income for the year stays below the SMI (article 38 ter of the Self-Employment Statute). In 2026 the threshold is €17,094, and under the 2027 draft it would be €18,004. If the second reduced year straddles two calendar years, the condition is checked in each. The extension must be requested before the second year starts, with a declaration that income will be below the SMI.
Protection from garnishment
An amount equal to the minimum wage cannot be seized (article 607 of the Civil Procedure Act). The rule also covers income from self-employment. Up to 30% can be taken from the portion between one and two times the SMI, up to 50% between two and three, up to 60% between three and four, up to 75% between four and five, and up to 90% above five times the SMI. Employers need to know this too: if a garnishment order arrives for your employee’s wages, the amount equal to the SMI cannot be touched.
Hiring someone from abroad
An autónomo hires as a private individual. When sponsoring a worker from another country, they have to prove their own means (article 76 of the immigration regulations, RD 1155/2024). After paying the salary they must be left with at least 50% of the SMI a month if they have no dependants. A family of two needs 100% of the SMI, plus 25% for each additional member. If that worker is part-time, their annual pay must still be no lower than the full-time SMI (article 74).
If you are choosing between working as an autónomo and setting up a limited company (SL), our article “Autónomo or SL” includes advice from a lawyer.
SMI and residence permits: when the SMI counts and when the IPREM does
In 2004 the SMI was limited to its role as the minimum wage. A separate index, the IPREM, was created for benefits, allowances and income thresholds (RDL 3/2004). That is why many thresholds for foreign residents are based on the IPREM. In 2026 it stands at €600 a month: no new budget has been passed, so the figures from the 2023 budget still apply.
Based on the SMI:
- Arraigo sociolaboral (residence through work): one or more contracts paying at least the SMI or the convenio rate pro rata to hours, adding up to at least 20 hours a week (article 127 of the regulations).
- Arraigo socioformativo (residence through training): you can work up to 30 hours a week, paid at least the SMI or the convenio rate pro rata to hours (article 131).
- A first work permit as an employee, and the means of an employer hiring as a private individual (articles 74 and 76, covered above).
- The visa and residence permit for remote work for a foreign company (visado de teletrabajo de carácter internacional): income of at least 200% of the SMI a month, plus 75% of the SMI for a second family member and 25% for each additional one (Ministry of Inclusion FAQ, question 19).
200% of €1,221 is €2,442 a month. The FAQ gives no figure in euros, and if you take the monthly SMI including the share of extras, it comes to €2,849. Check which figure applies with the office where you submit your application.
Based on the IPREM:
- Family reunification (reagrupación familiar): 150% of the IPREM for a family of two, which is €900 a month, plus 50% for each additional member (article 67).
- Non-lucrative residence (residencia no lucrativa), with no right to work: 400% of the IPREM, which is €2,400 a month, plus 100% for each family member (article 62).
- Arraigo social through family ties: means of at least 100% of the IPREM (article 127).
Two more rules are linked to the SMI. If an employer becomes insolvent, the FOGASA fund pays wage arrears of up to twice the daily SMI including the share of extras, for a maximum of 120 days (article 33 of the Workers’ Statute). And regional and municipal rules, as well as private contracts, that use the SMI as an income threshold do not pick up the new amount automatically. In 2026 they keep using the previous SMI (€1,184 a month, the 2025 amount) unless the rule or contract itself says otherwise (transitional provision of the decree).
What employers should check before January
- Compare salaries with the convenio and with the annual SMI, bonuses and supplements included.
- Budget for the rise. If the draft is approved, a full-time minimum-wage employee will cost about €1,202 more a year: €23,792.20 instead of €22,589.76 at the 1.50% rate. This uses the 2026 contribution rates, as the 2027 rates will be set in a separate order.
- If the decree is approved, pay hourly domestic staff at least €10.06 an hour from January.
- Wait for the BOE: the exact amounts and start date will only be confirmed once the decree is published.
This guide reflects the rules as of 15 November 2026. For your own case, especially the convenio and the AT/EP rate, ask a gestor (accountant/adviser) to run the numbers.
Cover photo: entrance to the Ministry of Labour and Social Economy, Madrid, Paseo de la Castellana, 63. Source: Gabinete de Comunicación del Ministerio de Trabajo y Economía Social, Wikimedia Commons. Horchatería photo: MollySVH, Wikimedia Commons, CC BY 2.0, resized.
Frequently asked questions
What is the minimum wage in Spain in 2026?
€1,221 a month over 14 payments a year, which is €17,094 a year or €40.70 a day. If the extras are spread across the year, it is €1,424.50 a month. The amounts were set by Royal Decree 126/2026 and apply from 1 January 2026.
Will the minimum wage be €1,286 in 2027?
That is what the Ministry of Labour proposes, and comments on the draft are accepted until 16 November 2026. The amount becomes binding once the Council of Ministers approves it and it is published in the BOE. Under the draft it would apply from 1 January 2027.
Why does the SMI keep going up when my salary doesn’t?
The government sets the minimum by decree every year. By law it has to take into account prices, productivity and the state of the economy (article 27 of the Workers’ Statute). The government has also set itself the goal of keeping the SMI at 60% of the average wage. The expert committee put the average net full-time wage for 2026 at €27,349 a year, and 60% of that is €16,409. Other salaries depend on the convenio and the employer. If you already earn more than the minimum over the year, the decree does not oblige your employer to give you a rise.
What is the minimum wage in Spain per hour?
The decree sets no general hourly rate. The minimum is calculated per month or per day for a full legal working week, and pro rata to hours for part-timers. The decree does separately set €9.55 an hour for domestic staff paid by the hour and €57.82 per working day for temporary contracts of up to 120 days.
How much does a minimum-wage employee cost?
On a permanent contract at the 1.50% AT/EP rate, about €22,590 a year: €17,094 in salary and €5,495.76 in employer contributions, an average of €1,882.48 a month. The employee takes home €15,982.92 a year.
Do I need a job paying at least the SMI for arraigo?
For arraigo sociolaboral, yes: the contract must pay at least the SMI or the convenio rate pro rata to hours, for a total of at least 20 hours a week. The thresholds for family reunification and non-lucrative residence are based on the IPREM.
This version of the article was translated from Russian with the help of AI.
SunClub Business directory

Legal services
Professional legal services in Spain. Arranging and renewing all types of residence permits
- Languages
- Russian, Ukrainian, Spanish, English
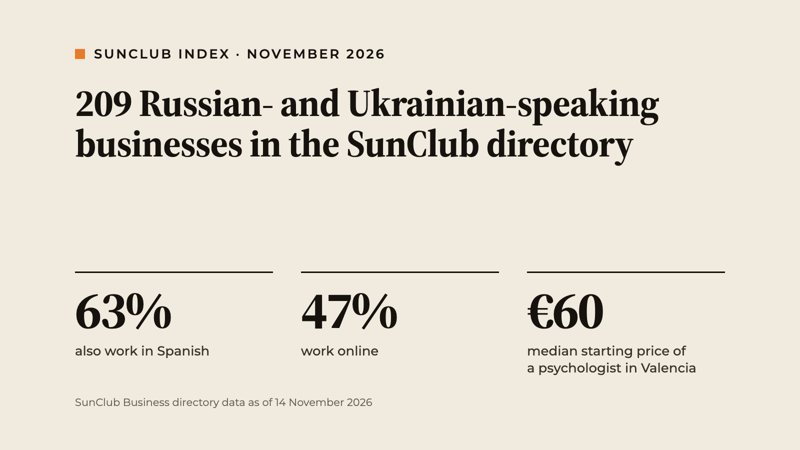
SunClub Business is the directory run by SunClub Network magazine: 240 businesses and professionals in Spain. The editors review every business page before it goes live. Browse the directory →