7 mistakes when buying property in Spain: Oleg Grechko of SFERO explains
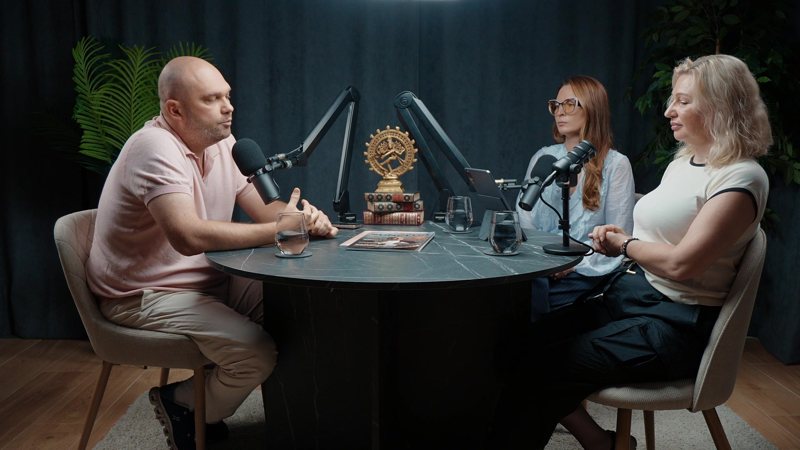
Waiting for prices to crash, choosing a flat before the mortgage is approved, buying from photos online. Oleg Grechko, founder of the SFERO Real Estate agency in Valencia, goes through seven mistakes that cost home buyers in Spain dearly. He gave this advice in spring, in an interview with SunClub Network magazine, and in autumn on the SunClub podcast. He covers prices in Valencia and Castellón, the 35% rule for mortgages, and derramas (building repair levies) on resale homes.
Partner content. Prices and terms as of the publication date.
Sfero Real Estate in the SunClub Business directory: contacts and services →

In this article
In brief: seven mistakes
- Waiting for prices to crash. Oleg Grechko does not expect a crisis like the one in 2008: at worst, prices will dip by 5–10% or stand still.
- Turning down a flat because the bedrooms are small. A typical Spanish two-bedroom flat is about 65 m², a three-bedroom one about 90 m².
- Choosing a flat before the mortgage is approved. The repayment can be no more than 35% of household income, the deposit is 20 to 40% and the bank takes about two months to decide.
- Hunting for a flat by the sea for €100,000.
- Buying a home to live in without ever having stayed in the area.
- Renovating a flat bought for resale to suit your own taste.
- Not checking for derramas: a levy for building repairs can pass to the new owner.
Mistake 1: waiting for prices to fall
Plenty of people put off buying. The market is overheated, they reason, so it is better to wait until prices collapse. Oleg Grechko, who founded the Valencia estate agency SFERO Real Estate, sees this as the easiest way to miss out on a good flat.
“Look at similar cities in other European countries. Prices there are much higher. Compared with them, Spain looks sensible, and we’re a long way from overheating,” says Oleg. Prices climbed steeply from 2018, especially in 2022. Growth has slowed since, but in his view the market still has room to rise.
In spring 2026 Oleg gave these figures: a good flat in Valencia itself costs €400,000–500,000, and a good new build in the suburbs around €350,000.
He does not expect a repeat of the 2007–2008 crisis. Banks are far stricter about lending, and the economy is on firmer ground. “The most that can happen is a dip of 5–10% or stagnation. People who spend years waiting for the bubble to burst still buy in the end, only for more money.”
 54 min
Key moments
- 0:00 You can’t buy anything here for €100,000
- 0:30 Who Oleg is and the episode’s two big questions
- 0:57 A planned move: from Warsaw to Valencia
- 1:41 How long it took to earn his first money in Spain
- 2:39 What surprised him in year one: red tape and timelines
- 4:22 If you’re not 1,000% sure, don’t start
- 6:13 Why property: poor service at viewings
- 7:09 First deal: a seafront flat in Oropesa del Mar
- 8:12 Six months to the first client and nearly €100,000 in the red
- 10:44 A late-night idea and training: what an agency is liable for in Spain
- 12:12 Who to hire first and why building a team is hard
- 13:03 A client with €250,000: the options
- 14:46 Long-term letting and living there yourself: why it doesn’t work
- 16:03 Why flipping is dead
- 18:34 Where the margin is now: new builds
- 19:06 Will the building get finished? How buyers’ money is protected
- 20:39 Buying costs: 9% ITP, notary, land registry, agency
- 21:42 The owners’ meeting minutes: how not to inherit someone else’s debt
- 22:46 Why use an agency when Idealista exists
- 23:59 Squatters (okupas): how they find flats
- 25:12 Types of squatters and rent default insurance
- 27:15 Case study: squatters left in 2 hours for €4,000
- 29:40 Why landlords ask for your employment contract
- 32:34 Mortgages for non-residents: deposit and income
- 33:33 Mortgages for people under temporary protection
- 34:02 What banks look at: 2-year contract, 3 years as autónomo
- 35:08 The 35% rule and flats up to €150,000 near Valencia
- 37:44 How long a seller will wait for your mortgage: 3-month arras
- 39:46 The age limit for getting a mortgage
- 39:56 Difficult deals and unrealistic expectations
- 42:36 €100,000 by the sea: expectations vs the market
- 43:57 476 videos in a year: why being visible saves a business
- 46:33 News vs niche videos: reach vs leads
- 47:42 Why Oleg signed an annual contract with the print magazine
- 50:03 SunClub promo code: a consultation with the founder
- 50:48 Three tips for starting a business in Spain
- 52:21 A2 Spanish and why there’s no way back
- 53:50 Next episode preview
Mistake 2: rejecting a flat because the bedrooms are small
People move to Spain with the habits they grew up with: big rooms and a living room that can seat twenty guests. A Spanish flat is laid out differently.
“Spaniards hardly spend any time at home. Work in the morning, a terrace in the afternoon, a café with friends in the evening. The weather here never keeps you shut indoors. A flat is basically somewhere to sleep,” Oleg explains.
A typical two-bedroom flat is about 65 m², and a three-bedroom flat about 90 m². The main bedroom is 15 m² at most, and the second and third can be 9 m² or even 6 m². Developers build for what the Spanish middle class wants.
If the flat is meant for letting or selling on, Oleg advises putting your own taste aside. The market wants compact, practical homes that sell fast and are easy to let.
Mistake 3: finding a flat first and going to the bank later
Many people are sure that a foreigner will never get a mortgage in Spain, so they do not even apply. Oleg calls this a myth. The bank looks at your declared income and at the currency you earn it in: euros, dollars, pounds or zloty. With a good employment contract your chances are high. It is harder for business owners and autónomos (the self-employed), but they get mortgages too.
In autumn, on the SunClub podcast, Oleg went into more detail: banks have become stricter. Santander, for example, now asks employees for a contract of at least two years, and an autónomo needs three years of trading.
The bank works to one firm rule: the monthly mortgage payment can be no more than 35% of the household’s net income. Foreigners usually put down a deposit of 20 to 40% of the price.
The most common slip, though, is doing things in the wrong order. People find their dream flat, then go to the bank, and approval takes about two months. Not every seller will wait that long. Oleg’s advice is to get the bank’s pre-approval first and only then start viewing. If the seller agrees to wait, you can write more time into the deposit contract (contrato de arras): Oleg negotiates as much as three months.
What banks ask of residents, non-residents and Ukrainians with temporary protection is covered in our guide “Mortgages in Spain for foreigners in 2026”.
Mistake 4: expecting a flat by the sea for €100,000
This is how Oleg sums up a typical client request: “I want a three-bedroom flat by the sea for under €100,000. With a pool, underground parking, a brand-new designer renovation and three-metre ceilings.” Spain has not had prices like that for a long time.
In Barcelona, Oleg reckons, a flat you would actually want to live in starts at €1.2 million. With a smaller budget, he suggests looking at other cities, such as Castellón de la Plana: around 180,000 inhabitants, the sea close by, a university and an airport. According to Oleg, there are no tourist crowds, and a good flat can be bought for €250,000.
On the podcast Oleg explained in detail what you can realistically find near Valencia for €100,000–150,000. The figures and the areas are in “Buying property in Valencia: what €100,000 really gets you”.
Mistake 5: buying from pictures without knowing the area
Someone sees beautiful photos online and buys a flat sight unseen. Then it turns out that in summer children shriek by the pool under the window from morning till night, in autumn the area empties and the restaurants shut, and in winter a biting wind blows in off the sea.
“If you’re buying for yourself, come for a month first. Rent a flat in that area, walk the streets, get a feel for what life there is like. In real life things often look nothing like the tourist brochure,” Oleg advises.
Mistake 6: renovating a flat to sell as if you were going to live there
An investor buys a flat to resell, then renovates it to their own taste. Say, an expensive designer job in an old building with no lift on the edge of town. They pour a lot of money in, put the flat on the market at €300,000 and cannot see why nobody has bought it after a year.
“The market has no use for that. You have to work out with a cool head what people are buying right now and what will pay for itself fastest,” says Oleg.
On the podcast he went further and called flipping dead. For a private investor, buying an old flat, renovating it and selling it on now brings in almost nothing. Sellers have put their prices up, renovation costs more and tax swallows the profit. The most money right now, he says, is made on new builds bought as soon as sales open.
Mistake 7: not checking for derramas
There is one cost on the resale market that buyers think about last of all. It is the derrama: a sum the owners of a building vote to collect from every flat to pay for work on the façade, the roof, the lift or the entrance hall.
Oleg describes a familiar story. You buy a flat in an old building, someone adds you to the neighbours’ group chat, and the administrator writes: “Welcome to our new neighbour! You owe €10,000 for the façade repairs.” The work was voted through under the previous owner, and the bill landed on you. Sellers tend to stay quiet about decisions like these.
You can protect yourself in two ways. Before you pay the deposit, ask the seller for the minutes of the latest owners’ meeting (acta de la junta) and read what was decided. “If you’re looking without an agency, always ask the seller, or the seller’s agency, for the latest meeting minutes. You’ll find out everything there,” Oleg says. He also advises writing into the deposit contract, in so many words, that the flat has no payments or derramas already agreed.
Check for old debts separately. By law, the flat itself is liable for the previous owner’s unpaid community fees for the current year and the three years before it. That is why the seller brings a certificate from the building administrator to the signing at the notary, stating that nothing is owed to the owners’ community (certificado de deuda de la comunidad). Ask for it in advance.
At SFERO, Oleg says, every property is checked before the deal goes through, because the agency’s reputation depends on it. For the other payments a buyer faces on top of the price of the flat, see our breakdown “Costs of buying property in Spain in 2026”.
Frequently asked questions
Will property prices in Spain fall?
Oleg Grechko does not expect a crash like the one in 2008: banks lend more strictly and the economy is more stable. At worst, he thinks, prices will dip by 5–10% or stop rising.
Do Spanish banks give mortgages to foreigners?
Yes, if your income is declared and in a stable currency. The repayment must stay within 35% of the household’s net income, and the deposit is usually 20 to 40%. Get the bank’s pre-approval before you start looking for a flat.
What is a derrama when you buy a flat?
It is a charge on the owners in a building to pay for repairs: the façade, the roof, the lift. If the work was agreed before you bought and the payment falls due afterwards, the bill can come to you. Read the minutes of the latest owners’ meeting before you pay the deposit.
How much does a flat in Valencia cost in 2026?
In spring 2026 Oleg Grechko valued a good flat in Valencia itself at €400,000–500,000 and a new build in the suburbs at about €350,000. In autumn, on the podcast, he also gave the lower end of the market: for about €150,000 you can find a two-bedroom flat in a building from the 1970s in the suburbs.
Where to find Oleg Grechko
Oleg Grechko founded the SFERO Real Estate agency and heads its sales. The agency works in Valencia, on the Costa Blanca and on the Costa del Azahar. Oleg talked about buyers’ mistakes in the spring issue of SunClub Network magazine and came on the SunClub podcast in autumn.
- Business page in the SunClub Business directory: SFERO Real Estate
- Agency website, with an English version: sfero.es
- Instagram: @sfero.realestate
- YouTube: @GrechkoOlegES
The full podcast episode is on YouTube: “Property in Spain 2026: why flipping is dead, squatters and mortgages” (in Russian).
This version of the article was translated from Russian with the help of AI.
SunClub Business directory

Sfero Real Estate
We help you buy, sell and invest in property, and take care of rental management and renovations with full turnkey support.
- Where
- Valencia
- Languages
- Russian, Ukrainian, Spanish, English, German
SunClub Business is the directory run by SunClub Network magazine: 240 businesses and professionals in Spain. The editors review every business page before it goes live. Browse the directory →
 Buying property in Valencia: what €100,000 really gets you, with Oleg Grechko of SFERO
 Mortgages in Spain for foreigners in 2026: income, deposit and age limits
 Costs of buying property in Spain in 2026: taxes, fees and worked examples
 A Spaniard could lead the ECB: what it means for your mortgage in Spain