Mortgages in Spain for foreigners in 2026: income, deposit and age limits
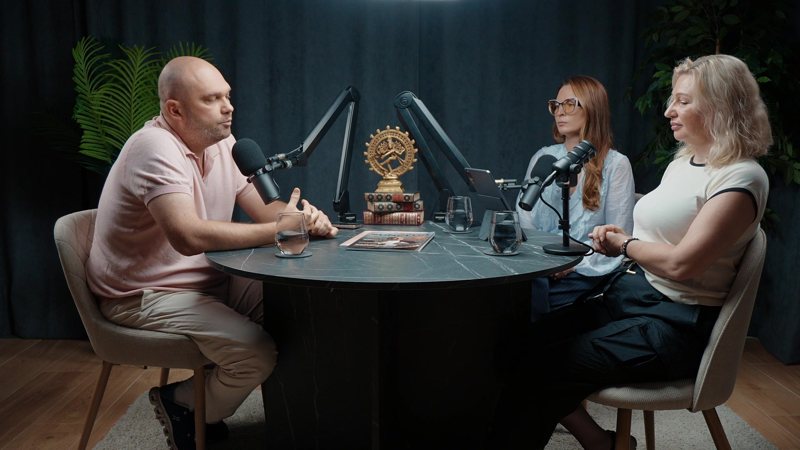
A mortgage in Spain for foreigners is a perfectly realistic plan. On the SunClub podcast (in Russian), estate agent Oleg Grechko explained what income you need, what deposit banks ask of residents and non-residents, whether Ukrainians with temporary protection can get a mortgage and how to avoid losing your deposit while the bank makes up its mind.

In brief: mortgages in Spain for foreigners in 2026
- Spanish banks lend both to people who live here and to non-residents. What matters most is official income.
- Mortgage repayments must not exceed 30–35% of income.
- Banks usually lend residents up to 80% of the property’s value and non-residents 60–70%. That means a deposit of anywhere from 20% to 30–40%, plus the purchase costs.
- By the final payment the borrower must be no older than 70–80, depending on the bank. The term is up to 30 years, more often up to 25 for non-residents.
- Approval takes one to two months.
Can a foreigner get a mortgage in Spain?
Yes, even though the idea that they can’t is one of the most stubborn myths among people who have moved here. “It’s doable, more than doable. You don’t even have to live here,” says Oleg Grechko, founder of the SFERO Real Estate agency in Valencia, on the SunClub podcast (in Russian).
What the bank cares about is income rather than citizenship: official, documented and in a stable currency. “The question isn’t where you prove your income, it’s what currency you’re paid in: euros, pounds, dollars, zloty,” Oleg explains. If your income is in another currency, the bank usually builds in a margin for exchange-rate swings.
 54 min
Key moments
- 0:00 You can buy nothing here for €100,000
- 0:30 Who Oleg is and the episode's two big questions
- 0:57 A planned move: from Warsaw to Valencia
- 1:41 How long it took to earn his first money in Spain
- 2:39 What surprised him in year one: red tape and timelines
- 4:22 If you're not 1,000% sure, don't start
- 6:13 Why property: poor service at viewings
- 7:09 First deal: a seafront flat in Oropesa del Mar
- 8:12 Six months to the first client and nearly €100,000 in the red
- 10:44 A late-night idea and training: what an agency is liable for in Spain
- 12:12 Who to hire first and why building a team is hard
- 13:03 A client with €250,000: the options
- 14:46 Long-term letting and living there yourself: why it doesn't work
- 16:03 Why flipping is dead
- 18:34 Where the margin is now: new builds
- 19:06 Will the building get finished? How buyers' money is protected
- 20:39 Buying costs: 9% ITP, notary, land registry, agency
- 21:42 The owners' meeting minutes: how not to inherit someone else's debt
- 22:46 Why use an agency when Idealista exists
- 23:59 Squatters (okupas): how they find flats
- 25:12 Types of squatters and rent default insurance
- 27:15 Case study: squatters left in 2 hours for €4,000
- 29:40 Why landlords ask for your employment contract
- 32:34 Mortgages for non-residents: deposit and income
- 33:33 Mortgages for people under temporary protection
- 34:02 What banks look at: 2-year contract, 3 years as autónomo
- 35:08 The 35% rule and flats up to €150,000 near Valencia
- 37:44 How long a seller will wait for your mortgage: 3-month arras
- 39:46 Up to what age you can get a mortgage
- 39:56 Difficult deals and unrealistic expectations
- 42:36 €100,000 by the sea: expectations vs the market
- 43:57 476 videos in a year: why being visible saves a business
- 46:33 News vs niche videos: reach vs leads
- 47:42 Why Oleg signed an annual contract with the print magazine
- 50:03 SunClub promo code: a consultation with the founder
- 50:48 Three tips for starting a business in Spain
- 52:21 A2 Spanish and why there's no way back
- 53:50 Next episode preview
How much the bank will lend: the 35% rule
The main limit: your monthly mortgage repayment must not exceed roughly 35% of your income. Some banks work to 30%.
Oleg gives an example: “Even if you earn 1,500, you can take a mortgage with a 500-euro repayment. That’s a flat up to about 150,000.” The maths adds up: at around 3% a year over 30 years, a repayment of €525 a month corresponds to a loan of about €125,000. Together with a 20% deposit, that is enough for a flat of around €150,000.
In Valencia itself there is almost nothing at that price, but in suburbs such as Burjassot, Mislata or Sagunto you can find a two-bedroom flat in a 1970s block. More on prices in Buying property in Valencia: what €100,000 really gets you.
Deposit: 20% or 40%
If you live in Spain and are buying a home for yourself, the bank will usually finance up to 80% of its value, so the deposit starts at 20%. Banks tend to lend non-residents from EU countries up to 70%, and everyone else around 60%.
“You need to count on a deposit of at least 20%, especially if you’re not resident and don’t live here. And it can even go up to 40,” Oleg says. Schemes offering 100% finance do exist, but in practice, he says, banks still ask for at least 10%.
Add the purchase costs to the deposit: tax, notary, registration. For a resale home in the Valencian Community that comes to about 10–12% of the price. There is a detailed breakdown in Costs of buying property in Spain in 2026.
What income the bank counts
- Employees. According to Oleg, banks have tightened their requirements: a one-year contract used to be enough, now they more often ask for at least two years.
- Autónomos (the self-employed). The bank looks at declared income over several years, and Oleg talks about three.
- Undocumented income does not count: neither transfers from friends nor cryptocurrency. “No paperwork, no deal. Want a mortgage? Go and work on the books,” is Oleg’s reply when asked about online income.
The usual paperwork: passport and NIE (foreigner identity number), an employment contract or autónomo returns, proof of income, bank statements for recent months and income tax returns.
Mortgages for Ukrainians with temporary protection
For people living in Spain under temporary protection and renting, Oleg recommends a mortgage without hesitation: “Yes, definitely. A mortgage will cost you less than renting.” The monthly repayment often comes out noticeably lower than the rent on the same flat.
The conditions are the same as for other residents: official income, an employment contract, a deposit and the purchase costs. Temporary protection for Ukrainian citizens in Spain has been extended until 4 March 2027. Before you apply, ask the bank how it treats the expiry date on your document, because banks differ on this.
Age limit and mortgage term
Mortgages are granted for a maximum of 30 years, more often 25 for non-residents. By the last payment the borrower must be no older than 70–80, with the exact cut-off depending on the bank. If you are 50, the realistic term is 20–25 years, and the repayments will be higher.
How long approval takes and how not to lose your deposit
From application to getting the mortgage usually takes one to two months. Sellers are not always prepared to wait, so it pays to agree terms in advance.
“When you sign the arras [the deposit contract], you can set it for three months. That’s completely legal. And we also write in that if the buyer gets, say, two rejections from banks, the arras is returned, even though by law it doesn’t have to be,” Oleg explains.
Safer still is to get the bank’s pre-approval before you start looking: then you know your budget for certain.
A new build as a way to get mortgage-ready
Spanish developers offer interest-free instalments. Before completion the buyer pays up to 40% of the price and the remaining 60% on receiving the keys, and almost everyone takes out a mortgage for that part.
“The bank counts the first 40% as the deposit, and you get a mortgage for the whole 60%. And while the building goes up, you have two years to get your income up,” Oleg says. In that time you can move to a longer contract or build up declared income as an autónomo.
Who pays the mortgage costs
Under the current rules, the bank pays the notary, registration, processing and the tax on the mortgage deed itself. The borrower pays for the property valuation (tasación) and, if needed, for their own copy of the documents. The tax on buying the property itself is still paid by the buyer.
Frequently asked questions
Can foreigners get a mortgage in Spain?
Yes. Banks usually lend residents up to 80% of the property’s value and non-residents 60–70%. The main conditions are official income in a stable currency and a repayment of no more than 30–35% of income.
Can Ukrainians with temporary protection get a mortgage?
Yes, if they have official income and an employment contract. Temporary protection has been extended until 4 March 2027, but banks take different views on how long the document is valid, so check this before applying.
What deposit do you need for a mortgage in Spain?
Usually from 20% for residents and from 30 to 40% for non-residents. On top of that come the purchase costs: for a resale home in the Valencian Community, about another 10–12% of the price.
What is the age limit for a mortgage in Spain?
The term is set so that the borrower is no older than 70–80 at the final payment, depending on the bank. The maximum term is 30 years.
About the expert
Oleg Grechko is the founder and sales director of SFERO Real Estate (Valencia, Costa Blanca, Costa del Azahar). Quote the promo code SunClub for a free one-to-one consultation with him. The full conversation is on the SunClub podcast on YouTube (in Russian), in the player above.
- Website: sfero.es
- YouTube: @GrechkoOlegES
- Instagram: @sfero.realestate
SunClub Business directory

Sfero Real Estate
We help you buy, sell and invest in property, and take care of rental management and renovation with full turnkey support.
- Where
- Valencia
- Languages
- Russian, Ukrainian, Spanish, English, German
SunClub Business is the directory run by SunClub Network magazine: 156 businesses and professionals in Spain. The editors review every business page before it goes live. Browse the directory →
 Buying property in Valencia: what €100,000 really gets you, with Oleg Grechko of SFERO
 Squatters in Spain in 2026: the new law, eviction costs and how to protect your home
 Costs of buying property in Spain in 2026: taxes, fees and worked examples
 Las Meninas by Velázquez: the meaning behind the painting and where to see it in Madrid